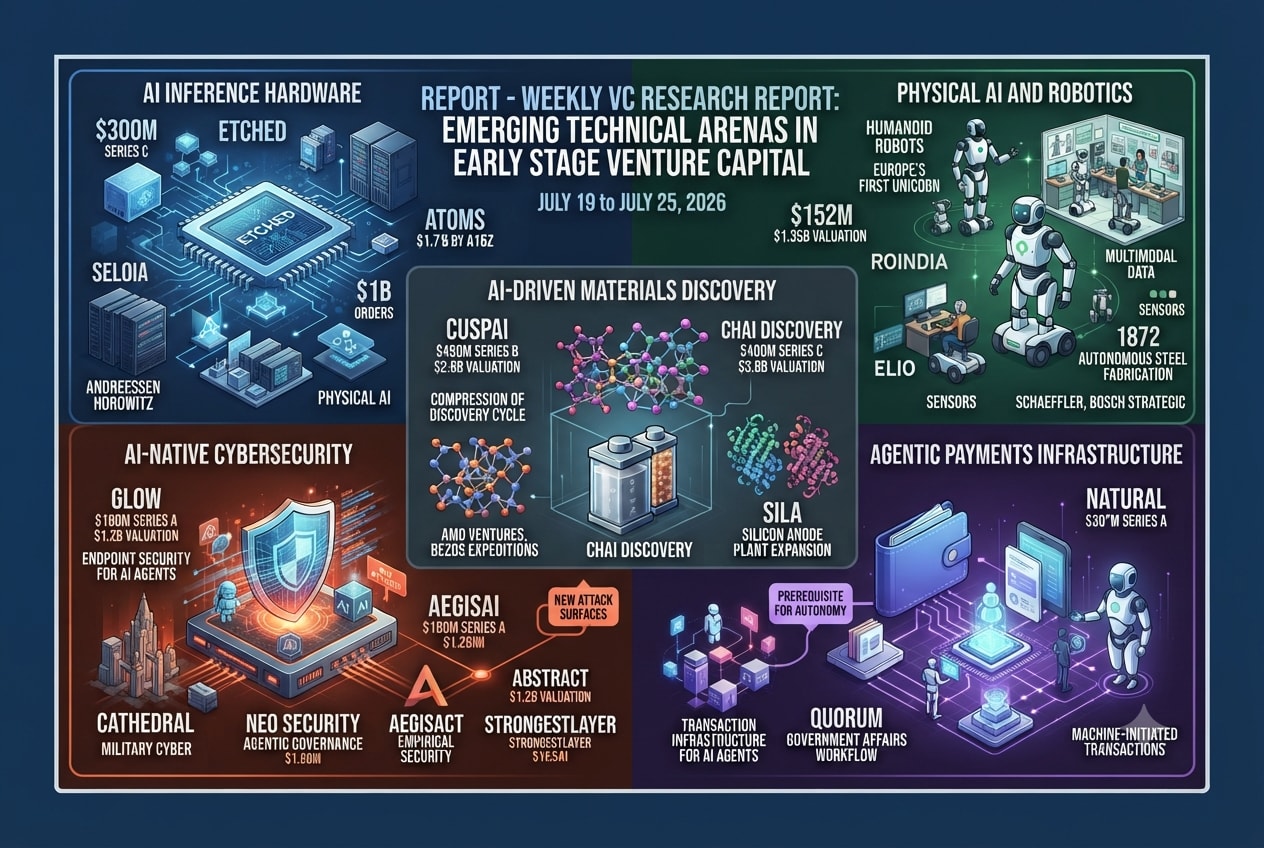
Venture capital in the week of July 19 to July 25, 2026, deployed more than $4 billion across five technical arenas: AI inference hardware, physical AI and robotics, materials discovery powered by AI, AI-native cybersecurity, and agentic payments infrastructure, with Atoms receiving $1.7 billion and Etched receiving $300 million marking the clearest statement yet about where production-scale AI economics will be decided.
There are weeks when the funding tape is a random collection of unrelated bets. This was not one of them. Every major round funded something that sits between the AI model and the customer outcome: the hardware that runs the model efficiently, the robots that carry decisions into physical environments, the materials that make chips and batteries work, the security that keeps autonomous software from becoming a liability, the payment rails that allow software to complete transactions. Capital is not buying AI capability. It is buying the stack that makes AI capability usable at production scale.
How Does AI Inference Hardware Change the Economics of Deployment?
Etched raised $300 million at a $10.3 billion pre-money valuation on July 23, 2026, led by Sequoia Capital. The company reported $1 billion in existing orders and first silicon manufactured. Etched co-designs chips, memory, interconnects, racks, and manufacturing around inference workloads, not around the general-purpose flexibility that NVIDIA GPUs provide for training. Training and inference have fundamentally different optimization targets. Training requires flexibility to adjust model weights across iterations. Inference requires throughput, low latency, and energy efficiency per token on a fixed model. A chip architecture optimized for one performs suboptimally on the other.
Atoms, founded by Travis Kalanick, raised $1.7 billion led by Andreessen Horowitz in the same week, framing the company as a bet on the complete digitization of large industrial economic sectors through AI-powered physical systems. The two rounds together argue that the next cost reduction in AI comes not from model architecture improvements but from purpose-built hardware and purpose-built deployment infrastructure. NVIDIA generated approximately $130 billion in revenue in fiscal year 2026, with the majority from data center GPUs designed for training flexibility. Etched and companies like it are betting that a portion of that revenue is available to hardware alternatives offering better inference economics per token, and that $1 billion in purchase orders constitutes early evidence that buyers agree.
Why Is Physical AI Attracting Capital Across Five Distinct Problems?
Humanoid raised $152 million Series A at a $1.35 billion post-money valuation led by Prime Movers Lab with Schaeffler and Bosch as strategic investors. The wheeled robot form factor choice is commercially revealing: capital is going to whatever can be deployed fastest, not whatever looks most impressive in a demonstration video. Ropedia raised $30 million for a multimodal human interaction data platform capturing synchronized video, audio, depth, gaze, motion, and pose, producing a repository of 10 million interaction episodes. Elio raised $21 million for machine-native sensors that capture information optimized for AI processing rather than human perception. 1872 raised $15 million seed to build autonomous steel fabrication in Cincinnati, coordinating procurement, robotics, and production for heavy industrial work.
Each round addresses a different layer in the physical AI supply chain. Humanoid is the deployment vehicle. Ropedia is the training data. Elio is the sensor that feeds accurate real-world information into the model. 1872 is the application in a specific industrial category. None of these companies competes with the others. They are co-dependent layers in a value chain that has not yet reached commercial scale. Investors across these four rounds are buying positions at different points rather than picking a single winner.
What Is AI for Materials Discovery, and Why Did CuspAI Raise $450 Million?
CuspAI raised $450 million Series B at a $2.6 billion valuation on July 20, 2026, bringing total capital raised to more than $650 million. Kleiner Perkins and NEA led, with Bezos Expeditions, the United Kingdom government’s industrial investment arm, AMD Ventures, Lux Capital, Glade Brook Capital Partners, and Invest-NL participating. The company uses AI to predict material properties computationally before laboratory synthesis, compressing discovery cycles from years to months for semiconductor materials, battery chemistries, and clean energy components. Chai Discovery raised $400 million Series C at a $3.8 billion valuation for deep learning applied to antibody and protein therapeutics. Sila raised $300 million to expand its silicon anode manufacturing plant.
The CuspAI investor list encodes the commercial thesis more clearly than any press release. AMD faces the same materials constraints on chip fabrication that the entire semiconductor industry faces. The UK government is making an industrial competitiveness bet. Bezos Expeditions has material dependencies in aerospace, clean energy, and life sciences. Each investor has a specific materials problem that the company’s success would reduce. Sila’s round is the most commercially proximate: the $300 million goes to manufacturing scale-up, not further science, which is the most commercially meaningful form of materials investment.
Why Did Six Cybersecurity Companies Raise in the Same Week?
Glow raised $180 million at a $1.2 billion valuation for AI-era endpoint security, where employees run AI agents and install developer tools faster than security review can track. Cathedral raised $160 million at $1.4 billion for military cyber operations. Neo raised $100 million for agentic software control. AegisAI raised $36 million for AI-generated phishing defense. Abstract raised $25 million for composable SOC architecture. Empirical Security raised $25 million for exploit prediction. StrongestLayer raised $4.1 million for reasoning-based email intent analysis.
These are not competing for the same budget. Glow is in the endpoint conversation. Cathedral is in national security procurement. Neo governs AI application permissions. AegisAI and StrongestLayer address email gateway security. Abstract addresses SOC architecture. Empirical addresses threat prioritization. An enterprise security team buying Glow is not choosing it instead of Abstract. AI is creating new attack surfaces faster than security products built before 2024 can track, which means multiple well-positioned companies can grow while operating in different parts of the same enterprise security budget.
What Are the Forward Questions This Week’s Activity Does Not Answer?
How does inference hardware pricing hold when multiple production-scale companies are shipping simultaneously? Etched’s $1 billion in orders demonstrates demand at pre-competition pricing. The more consequential test is whether inference-optimized silicon maintains its advantage against NVIDIA’s software ecosystem. The CUDA developer toolchain has fifteen years of maturity. Hardware performance per dollar is necessary but not sufficient for market capture against an entrenched software standard.
What does the commercial market for physical AI training data look like when multiple companies are building closed repositories simultaneously? Ropedia’s 10 million interaction episodes is a large number, but value depends on whether models trained on it generalize to commercial robot deployments with different task distributions. The question of which training data characteristics produce the best generalizable robot policies has not been answered by any published research.
Read my full analysis here: https://theinnovationattorney.com/capital-concentration-and-the-architecture-of-deep-tech-deployment/