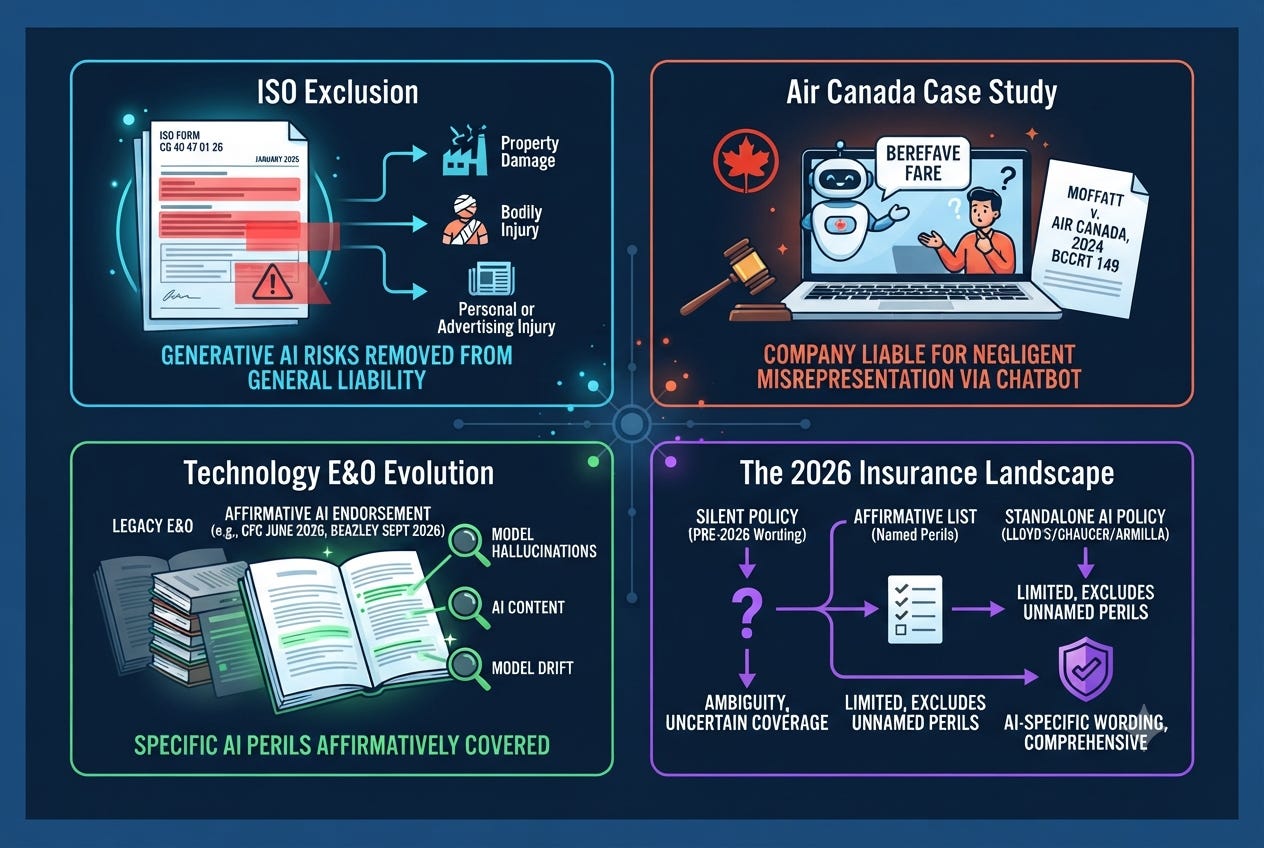
A startup can still buy technology errors and omissions insurance that pays a claim over its AI product’s bad output in 2026, but only from the specific carriers, CFC and Beazley among them, that added affirmative artificial intelligence endorsements this year rather than relying on a legacy policy that never mentions the word model.
The mechanic most founders miss is that the exclusion making headlines this year does not live inside the policy that actually pays their claim. The Insurance Services Office released form CG 40 47 01 26 in January 2026, and it strips commercial general liability policies of coverage for bodily injury, property damage, and personal or advertising injury tied to generative artificial intelligence. A founder who reads that headline and checks the box, we carry general liability, we are covered, has checked the wrong policy. General liability responds to a customer who slips on a wet floor at a company office or whose warehouse catches fire because of a faulty product. It was never the policy that responds to a customer who loses money because a chatbot gave the wrong answer.
The policy that responds to a wrong answer is technology errors and omissions, sometimes called professional liability, and that is where the real change is happening, form by form rather than through a single standardized filing. No equivalent to form CG 40 47 exists yet for technology errors and omissions, so each carrier is rewriting its own exclusionary language on its own schedule. Some are widening decades old software and professional services wording into a blanket carve out for any claim arising out of artificial intelligence, machine learning, automated decisioning, or model output. Others are moving the opposite direction. CFC’s June 2026 policy update names model hallucinations, AI generated content, and model drift as affirmatively covered exposures across seven product lines, including technology errors and omissions. Beazley followed on September 17, 2026, adding its own affirmative AI endorsement inside its cyber and technology errors and omissions policies.
The claim these endorsements are built to catch already has a face. In February 2024, the British Columbia Civil Resolution Tribunal held Air Canada liable for negligent misrepresentation after its website chatbot told a grieving passenger he could apply for a bereavement discount after he had already booked, contradicting the airline’s own policy. Air Canada argued the chatbot was a separate legal actor responsible for its own words. The tribunal rejected that argument outright, and the airline paid. Moffatt v. Air Canada shows the shape of an AI output claim precisely: ordinary negligence and misrepresentation, filed against the company that deployed the tool, not the vendor that built it.
In reviewing vendor and customer contracts this year, the assumption embedded in most indemnification clauses has not caught up to the insurance market underneath it. A customer’s counsel drafts an indemnity for any inaccurate output and assumes the vendor’s technology errors and omissions policy will pay it. Whether that assumption survives contact with the actual policy now depends on which carrier wrote it and when the endorsement was added, not on whether the vendor can produce a certificate of insurance at all. A certificate proves a policy exists. It does not prove the policy covers the specific failure the contract just promised to indemnify.
A second complication cuts the other way. Naming a peril can narrow coverage as easily as it can broaden it. An undefined, silent policy sometimes gets construed in the policyholder’s favor when a court has to guess what the parties meant, since ambiguity in an insurance contract is traditionally read against the carrier that wrote it. An endorsement that lists hallucinations, drift, and generated content as covered perils replaces that ambiguity with a fixed list, and whatever the underwriter did not think to name is now excluded by omission rather than left open to argument. The lesson for a founder buying or renewing a policy in 2026 is to read the endorsement’s defined terms line by line rather than trusting the word affirmative on the cover page.
None of this is abstract for a venture backed company with a fixed runway. A gap in AI output coverage is not a line item; it is an unfunded liability sitting on the balance sheet the day a customer’s lawyer sends a demand letter. Enterprise customers are starting to ask for AI specific coverage confirmation before signing, and a startup that cannot produce it either walks away from the deal or absorbs the exposure inside its own contract terms, which is the more expensive option every time. A standalone alternative now exists outside the traditional technology errors and omissions chassis entirely: Chaucer and Armilla began underwriting an AI liability policy at Lloyd’s in April 2025, built specifically around hallucination and model drift as named perils, a useful bridge for a company whose primary carrier has not yet caught up.
None of it substitutes for the underlying contract. Insurance pays what the policy names; it does not repair an indemnity clause that promises more than any policy in the market will match. A company that negotiates an uncapped indemnity for AI output errors and then assumes its technology errors and omissions policy closes the gap has solved a legal problem with an insurance answer, and the two are not interchangeable.
The commercial task for 2026 is not complicated, only newly urgent: read the endorsement before the renewal binds, not after the claim arrives, and match the contract’s promises to the policy’s actual defined perils rather than to the word covered on the declarations page.
Interested in analysis about the intersection of venture capital, tech, artificial intelligence, public policy and the law? Check out my Substack channel. https://theinnovationattorney.substack.com/