Founder Equity Pool Size and Vesting Terms at Company Formation
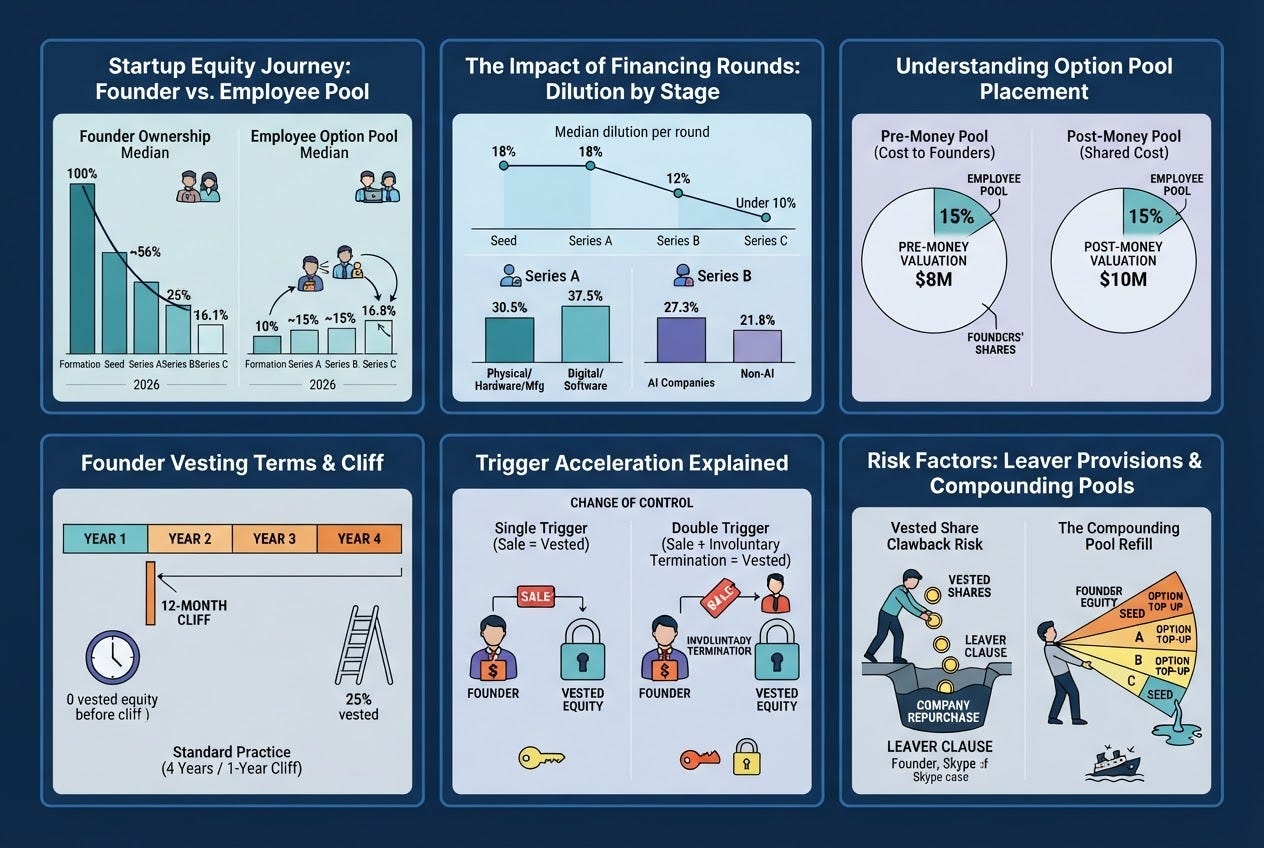
A founder who accepts a ten to fifteen percent employee option pool at formation without negotiating its placement on a post money basis, and who signs a standard four year vesting schedule with no double trigger acceleration, risks reaching a Series C financing holding less equity than the pool created to hire the company’s own staff. Venture financings closed through 2026 show a median founder holding 16.1 percent of a venture backed company at the Series C stage against a median employee option pool of 16.8 percent of that same company. The gap opens earliest in the two decisions a founder controls completely at formation: the size and placement of the option pool, and the vesting and acceleration terms attached to the founder’s own stock.
Executive Summary
In 2026, the median startup founder holds 16.1 percent of a venture backed company whose own employee option pool holds 16.8 percent by the Series C round. A founder negotiating formation documents should fix the initial employee option pool at approximately 10 percent of fully diluted equity, sized against an eighteen month hiring plan, not an investor’s standard template, and should insist the pool sit on a post money basis so new investors share its cost. Founder vesting should run four years with a twelve month cliff, matching the term the venture industry’s own standard form documents recommend for every other option holder, paired with double trigger acceleration that vests the founder in full only if a change of control is followed by an involuntary termination or a material cut to title or pay.
Median founder ownership falls from approximately 56 percent after a seed round to 36 percent after a Series A round, then into the high twenties or low twenties by a Series B round, before reaching 16.1 percent at Series C. Each decline compounds two separate mechanics: the capital raised at each round, and the employee pool that investors require the company to create or refresh immediately before that round prices. A founder who negotiates pool size once, at formation, and then accepts whatever pool refresh a term sheet proposes at every later round, surrenders control over the second mechanic entirely. The practice described below, sizing the pool to an actual hiring plan, placing it on a post money basis, and fixing founder vesting on terms no worse than the employee pool itself receives, reflects established market practice rather than an aggressive founder position, and it is available to any founder willing to negotiate it before signing a term sheet.
Detailed Findings
Capital Structure and Pool Sizing at Formation
An employee option pool is almost always sized on a pre money basis at formation, which means the cost of creating it comes out of the founders’ side of the capitalization table before a new investor’s money is counted. A lead investor proposing a $2,000,000 seed investment on an $8,000,000 pre money valuation will routinely ask for a 15 percent pool to be added to that same pre money figure, so the investor’s ownership lands exactly where the term sheet states while the founders absorb the entire cost of the pool on top of the dilution the new money itself causes. Market practice through 2026 centers the initial pool between 10 and 15 percent of fully diluted equity, with 10 percent the single most common figure in seed stage financings, though a pool sized to an actual eighteen month hiring plan rather than to a generic percentage better protects a founder’s position than accepting whatever figure the term sheet proposes.
A stack of convertible instruments compounds the same mechanic before a priced round ever happens. Three stacked Simple Agreements for Future Equity of $500,000, $1,000,000, and $1,000,000 on progressively higher valuation caps commit roughly 20.1 percent of the company before a lead investor prices anything, a figure that converts to approximately 14.3 percent of the capitalization table once the notes convert at the seed price. A founder who tracks only the headline percentage a term sheet quotes, without modeling the combined effect of the convertible stack and the incoming option pool, consistently underestimates the true cost of a seed round by a wide margin.
Market and Valuation Context Across Financing Rounds
Founders begin a company owning all of it. By the close of a seed round, the median founding team holds approximately 56 percent of the fully diluted capitalization, a decline driven in roughly equal part by the capital sold to seed investors and by the employee pool, which stands at a median of approximately 12.1 percent of the company by that point. A Series A round cuts the median founder position further, to 36 percent overall, with founders of physical, hardware, and manufacturing companies retaining a median of only 30.5 percent against 37.5 percent for founders of digital and software companies, a gap that reflects the larger teams and capital commitments that physical product development requires before a first commercial sale.
By a Series B round, founders of artificial intelligence companies hold a median of 27.3 percent, against 21.8 percent for founders outside that category, reflecting the premium valuations and larger primary raises that rounds labeled as artificial intelligence commanded through 2025 and into 2026. The pattern inverts at Series C: founders hold a median of 16.1 percent of the company at that stage, while the employee option pool, refreshed at every intervening round to cover the hiring each new round of capital funds, holds a median of 16.8 percent, so the median Series C company’s own workforce owns more of the business than the people who started it.
Dilution recorded across roughly 1,000 venture financings closed in the year to July 2026 shows the heaviest single round losses concentrated early: a median seed round costs the existing capitalization table approximately 18 percent, matched by an equally sized loss at Series A, before dropping to roughly 12 percent at Series B and under 10 percent at Series C. Because the earliest rounds carry the largest percentage losses and arrive before a founder has revenue or a competing term sheet to negotiate from, the decisions made at formation about pool size and vesting terms shape every subsequent round more than any single decision that follows them.
Founder Vesting and Departure Risk
The investor rights agreement that most United States venture financings start from recommends four year vesting with a one year cliff for every option granted after the financing closes. Although that provision by its terms addresses future hires, lead investors in priced rounds today routinely ask founders to adopt the identical schedule for their own already issued stock as a closing condition, carried out through a separate founder restricted stock purchase agreement executed at the same time as the financing.
Vesting acceleration on a sale of the company comes in two forms. Single trigger acceleration vests some or all of a founder’s remaining shares immediately on the closing of a sale, regardless of what happens to the founder’s job afterward. Double trigger acceleration withholds that acceleration unless the sale is followed, within a fixed window ordinarily twelve months, by a second event, an involuntary termination without cause or a material reduction in title or compensation. Acquirers and the venture investors structuring a sale generally prefer double trigger provisions because they keep the founding team financially tied to the company through an integration period, and the provision protects the founder too: it closes off a buyer’s ability to force the founder out the day after closing while keeping the unvested stock.
The limits of vesting protection are evident in a 2005 dispute between Facebook and cofounder Eduardo Saverin. Facebook restructured from a Florida limited liability company into a Delaware corporation and issued a new round of stock under a 2005 stock purchase agreement that diluted Saverin’s position well below the share he and Mark Zuckerberg had agreed to at the company’s founding. Facebook sued Saverin over the agreement, Saverin countersued, and the parties settled out of court in 2009 on terms that remain confidential, with Saverin retaining public recognition as a Facebook cofounder. The dispute shows that a reincorporation, a recapitalization, or a new stock issuance can redraw a founder’s position as sharply as a financing round can, and that the paperwork executed at the moment of a corporate restructuring deserves the same scrutiny a founder gives a term sheet.
Risk Factors: Leaver Provisions and the Compounding Pool
A separate risk sits in how an option plan treats a departed holder before any exit occurs. When Microsoft purchased Skype for $8.5 billion in 2011 from the Silver Lake led investor group that had bought the company from eBay two years earlier, several former Skype employees, including former employee Yee Lee, discovered that a clawback provision in the company’s option plan allowed the company to repurchase vested shares from anyone who had left voluntarily before the sale closed. The provision was disclosed in the plan documents and was lawful, and it still caught departing employees who had not read the repurchase language closely enough to understand that vesting alone did not guarantee they would keep their shares through an eventual sale. A founder drafting the company’s own equity incentive plan controls whether that plan carries a similar repurchase right over vested shares, and should confirm that fully vested shares cannot be bought back for anything less than fair market value except in a termination for cause.
The pool a founder sizes at formation rarely survives to Series C unchanged. Investors at each subsequent round routinely request a pool top up calculated on a pre money basis, so the cost of the increase falls on the existing capitalization table before the new investor’s capital is counted into the valuation. A founder who signs each later pool top up without negotiating it surrenders the single largest lever on long run ownership to whichever investor leads the next round, which is precisely how a founding team that held a comfortable majority at formation can arrive at Series C holding less than the pool it built to staff the company.
Open Questions
1. Whether post money pool placement becomes the default opening position in seed and Series A term sheets. Lead investors today routinely propose the pool on a pre money basis as the starting position, placing the full cost on the founders before the new money is counted. A founder who negotiates post money placement shifts part of that cost onto the new investor, but this is not yet the default term, and which position becomes standard changes the founder ownership figures in this report by several percentage points at every round.
2. Whether double trigger acceleration becomes a closing condition investors propose rather than one founders must request. The provision already protects investors as much as founders by keeping a founding team in place through an integration period, so its spread as a standard term, rather than a negotiated one, would matter directly to any founder who has not yet raised an institutional round.
3. How the Series C founder and employee pool figures move once the artificial intelligence companies that raised unusually large early rounds in 2024 and 2025 begin reaching that stage in volume. Larger early rounds at premium valuations may produce either a smaller relative pool, because less new hiring is needed per dollar raised, or a larger one, because headcount growth at those companies has outpaced typical seed and Series A staffing plans.
4. Whether solo founders, a growing share of companies at formation, negotiate smaller or larger option pools than founding teams of two or more. A solo founder absorbs every pool increase alone rather than splitting its cost across cofounders, which changes the incentive to negotiate pool size and placement at formation.
5. Whether a leaver style repurchase right over vested shares, the mechanic at the center of the Skype option dispute, becomes a standard feature of equity incentive plans as more companies adopt plans drafted from the same small set of law firm templates. A founder who does not read the repurchase provisions in the company’s own plan may not learn the answer until an employee departure forces the question.
Source List
1. eBay Inc., press release filed as an exhibit to a Form 8-K, United States Securities and Exchange Commission, EDGAR system, 2009. Primary filing documenting the sale of Skype to the Silver Lake led investor group discussed in the Risk Factors section.
2. National Venture Capital Association, Model Legal Documents, Investor Rights Agreement, Section 5.3. The industry standard form document that sets the four year vesting and one year cliff baseline discussed in Founder Vesting and Departure Risk.
3. Carta, Founder Ownership Report 2026. The primary dataset behind every founder ownership and employee option pool percentage cited by financing round in this report.
4. Carta, Option Pools Guide: How to Size Your Employee Option Pool, 2026, citing HSBC Innovation Banking’s 2026 Term Sheet Guide. Source for current pool size ranges and the pre money option pool mechanic described in Capital Structure and Pool Sizing at Formation.
5. WaveUp, Startup Dilution per Round: 2026 Benchmarks by Stage, 2026. Aggregated dilution percentage data across approximately 1,000 venture financings closed in the year to July 2026.
6. SheetVenture, What Option Pool Sizes Are Standard at Different Stages, updated April 2026. Supplementary pool size ranges by financing stage.
7. Eisaiah’s Blog, Review: How Founder Friendly Are NVCA Model Legal Documents? Comparison to Founder Friendly Standard, 2021. Comparative analysis of the model vesting and acceleration provisions against a founder favorable standard.
8. Founders Workbench, The Skype Option Dilemma: Is There an Industry Standard?, 2011. Contemporaneous account of the option clawback dispute among former Skype employees.
9. Wikipedia, Eduardo Saverin, accessed October 2026. Chronology of the 2005 restructuring and 2009 settlement between Facebook and its cofounder.
10. California Startup Law Firm, Founder Dilution: Analyzing Saverin and the Social Network. Legal analysis of the mechanics behind the Facebook founder dilution dispute.
Bibliography
California Startup Law Firm. “Founder Dilution: Analyzing Saverin and the Social Network.” Accessed October 2026. https://www.calstartuplawfirm.com/business-lawyer-blog/founder-dilution-social-network.php.
Carta. “Founder Ownership Report 2026.” Carta, 2026. https://carta.com/data/founder-ownership-2026/.
Carta. “Option Pools Guide: How to Size Your Employee Option Pool.” Carta, 2026. https://carta.com/learn/startups/equity-management/option-pool/.
eBay Inc. Press release, Exhibit 99.1 to Form 8-K. United States Securities and Exchange Commission, EDGAR, 2009. https://www.sec.gov/Archives/edgar/data/1065088/000119312509227549/dex991.htm.
Eisaiah. “Review: How Founder Friendly Are NVCA Model Legal Documents? Comparison to Founder Friendly Standard.” Eisaiah’s Blog, June 10, 2021. https://eisaiah.blog/2021/06/10/review-of-nvca-model-legal-documents-comparison-to-founder-friendly-standard/.
Founders Workbench. “The Skype Option Dilemma: Is There an Industry Standard?” July 2011. https://www.foundersworkbench.com/about/resources/insights/2011/07/the-skype-option-dilemma--is-there-an-industry-sta.
National Venture Capital Association. Model Legal Documents. Accessed October 2026. https://nvca.org/model-legal-documents/.
SheetVenture. “What Option Pool Sizes Are Standard at Different Stages.” Updated April 11, 2026. https://sheetventure.com/fundraising-knowledge/what-option-pool-sizes-are-standard-at-different-stages.
WaveUp. “Startup Dilution per Round: 2026 Benchmarks by Stage.” 2026. https://waveup.com/blog/startup-dilution-per-round/.
Wikipedia. “Eduardo Saverin.” Accessed October 2026. https://en.wikipedia.org/wiki/Eduardo_Saverin.
Interested in analysis about the intersection of venture capital, tech, artificial intelligence, public policy and the law? Check out my Substack channel. https://theinnovationattorney.substack.com/