Positron AI closed an 875 million dollar Series C on September 10, 2026, at a 5 billion dollar valuation, and the round says nothing about how the company should paper its next customer deal. The commercial mechanic most founders building dedicated AI computing infrastructure miss is not the financing. It is the choice between selling a customer the hardware itself and selling the customer a metered slice of what that hardware produces, a choice that determines who owns the obsolescence risk, who certifies the export control paperwork, and who a lender will actually finance.
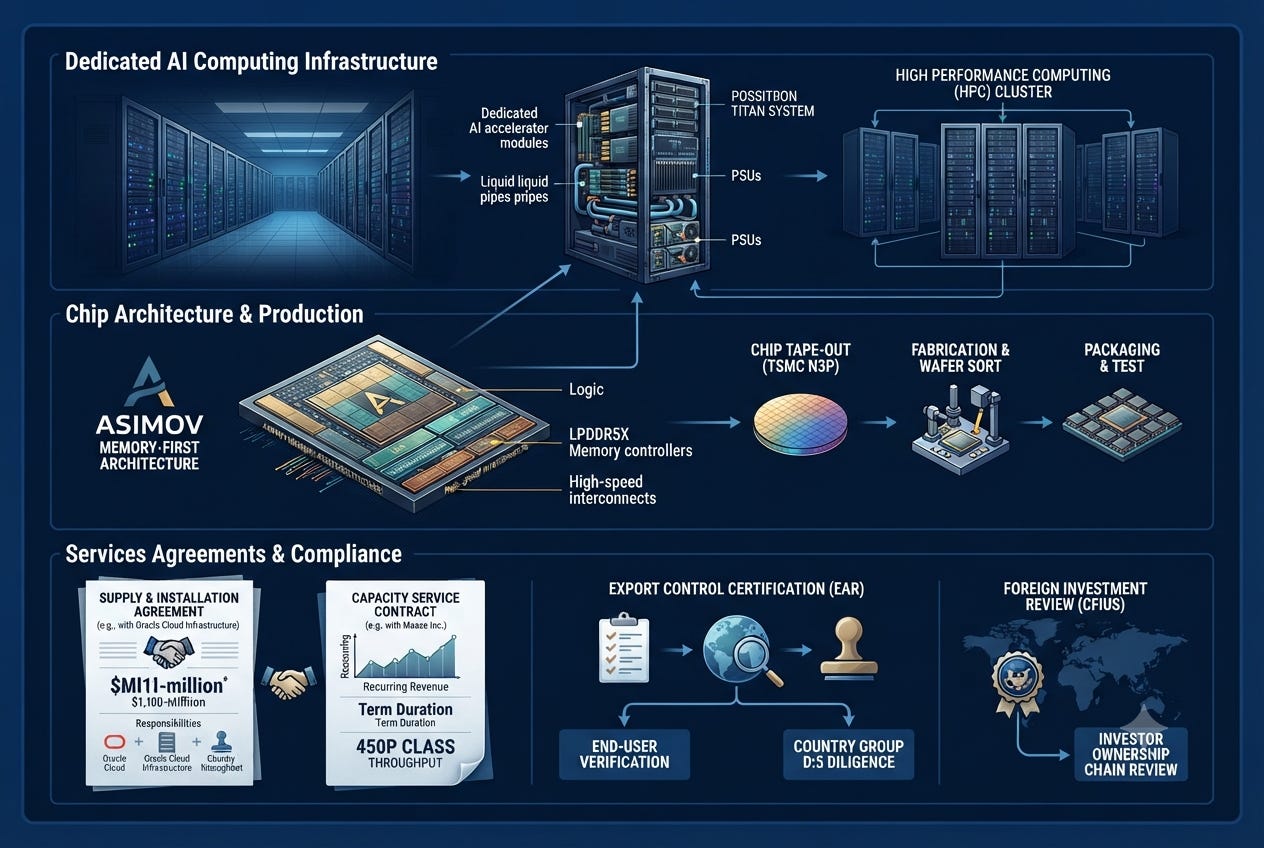
Positron builds an inference chip called Asimov that reaches more than 90 percent memory bandwidth utilization using ordinary LPDDR5X memory instead of the high bandwidth memory nearly every rival depends on, a design meant to sidestep a packaging bottleneck concentrated among a small number of Taiwanese suppliers. The Series C, split into a 375 million dollar tranche and a Series C 1 tranche of up to 500 million dollars, funds a chip tapeout on a Taiwan Semiconductor Manufacturing Company N3P node and a production ramp for systems already running inside Oracle Cloud Infrastructure. Seven months earlier, in February 2026, the company had raised 230 million dollars at just over a 1 billion dollar valuation. The capital trajectory is the easy part of this story. The contract trajectory is where the real work sits.
In April 2026, Positron disclosed that it was deploying tens of millions of dollars of Asimov based systems and racks directly into Oracle Cloud Infrastructure to run mixture of experts inference workloads, each system built around air cooled chips running at 450 to 500 watts and drawing roughly 3 kilowatts per rack. That agreement reads as a hardware supply and installation contract. Oracle takes the equipment, or a long term license to it, and Oracle operates it. Positron’s exposure ends at performance and warranty obligations on the silicon it sold.
Five months later, on September 15, 2026, a different company, Nasdaq listed Maase Inc., signed a twelve month agreement with Beijing based VirtAI Technology valued at approximately 10.8 million United States Dollars, an approximate conversion from the original non dollar contract figure. That agreement sells 450P class computing throughput under non sparse FP16 conditions, plus technical consulting, hardware troubleshooting, and platform maintenance, all measured against a fixed term rather than a fixed piece of equipment. Maase keeps the hardware. The customer buys capacity, not ownership.
Lenders underwriting dedicated computing hardware want two things: a customer contract whose cash flows survive a change in who operates the equipment, and a security interest in the equipment itself. A 260 million dollar, three year enterprise contract for 2,304 graphics processing units, signed in April 2026, shows what that looks like in practice: a fixed capacity commitment running years, not months, against a hardware count a lender can actually count. A supply and installation agreement like Positron’s Oracle deal produces exactly that kind of asset. A capacity service agreement like Maase’s VirtAI contract produces recurring revenue instead, which a different class of lender values on a different multiple. Neither is wrong. Signing one while drafting the other into the same contract is the mistake.
I have sat across the table from enough hardware vendors to know which clause gets skipped: the one stating what happens to a rack of chips at the end of the service term when the silicon is not broken, only superseded. Asimov’s own production life is already bounded. Positron’s proceeds fund a successor chip taping out on a newer process node before the current generation has finished its first full year inside an Oracle data center. A services agreement silent on that point leaves the customer holding depreciated hardware and the provider holding a support obligation neither side priced.
The company’s own patent position is the quieter risk. Asimov’s edge comes from running inference on ordinary LPDDR5X memory instead of the high bandwidth memory nearly every competing chip licenses, which sidesteps a packaging bottleneck concentrated among a small number of Taiwanese assembly and test providers. That architecture choice has not been tested against a memory controller patent dispute in open court, and a services agreement that assigns freedom to operate risk to the customer, rather than indemnifying the customer against it, will not survive a serious customer’s own review.
A single fact separates the two contract templates: the Bureau of Industry and Security’s interim rule of January 16, 2025 requires a license for advanced logic chips at 16 or 14 nanometers or below regardless of which contract structure a seller chooses. That rule, restated by the Bureau on May 31, 2026, reaches any end user whose corporate parent traces to Country Group D:5 or Macau, even when the entity physically receiving the chip sits somewhere else entirely. A services agreement, whichever template it follows, has to place a continuing ownership certification on the customer, because the seller, along with the buyer, answers to the Bureau if that certification turns out to be false.
Positron’s Series C included the Qatar Investment Authority and Naver Ventures alongside NEA, Atreides Management, and Valor Equity Partners, a lineup that puts a foreign investment review question on the table before the company signs its next customer. The Committee on Foreign Investment in the United States requires a mandatory filing when a foreign government controlled investor takes a substantial position in a business developing a critical technology, a category that reaches advanced semiconductor design. Whether a minority stake inside a nine figure round crosses that line depends on the investor’s actual board and information rights, a fact pattern a company’s own counsel can and should resolve before a customer’s due diligence team asks the question first.
None of this is settled by a bigger check. The 875 million dollars lets Positron tape out its next chip and ramp production of the systems already inside Oracle’s data centers, and it says nothing about which contract template the company’s general counsel should reach for when the next customer, in whichever country, wants dedicated silicon of its own. The next piece in this series takes up the mandatory declaration question directly: what a critical technology designation actually requires of a sovereign wealth fund’s minority stake in a semiconductor company, and what happens when nobody files.
Interested in analysis about the intersection of venture capital, tech, artificial intelligence, public policy and the law? Check out my Substack channel. https://theinnovationattorney.substack.com/