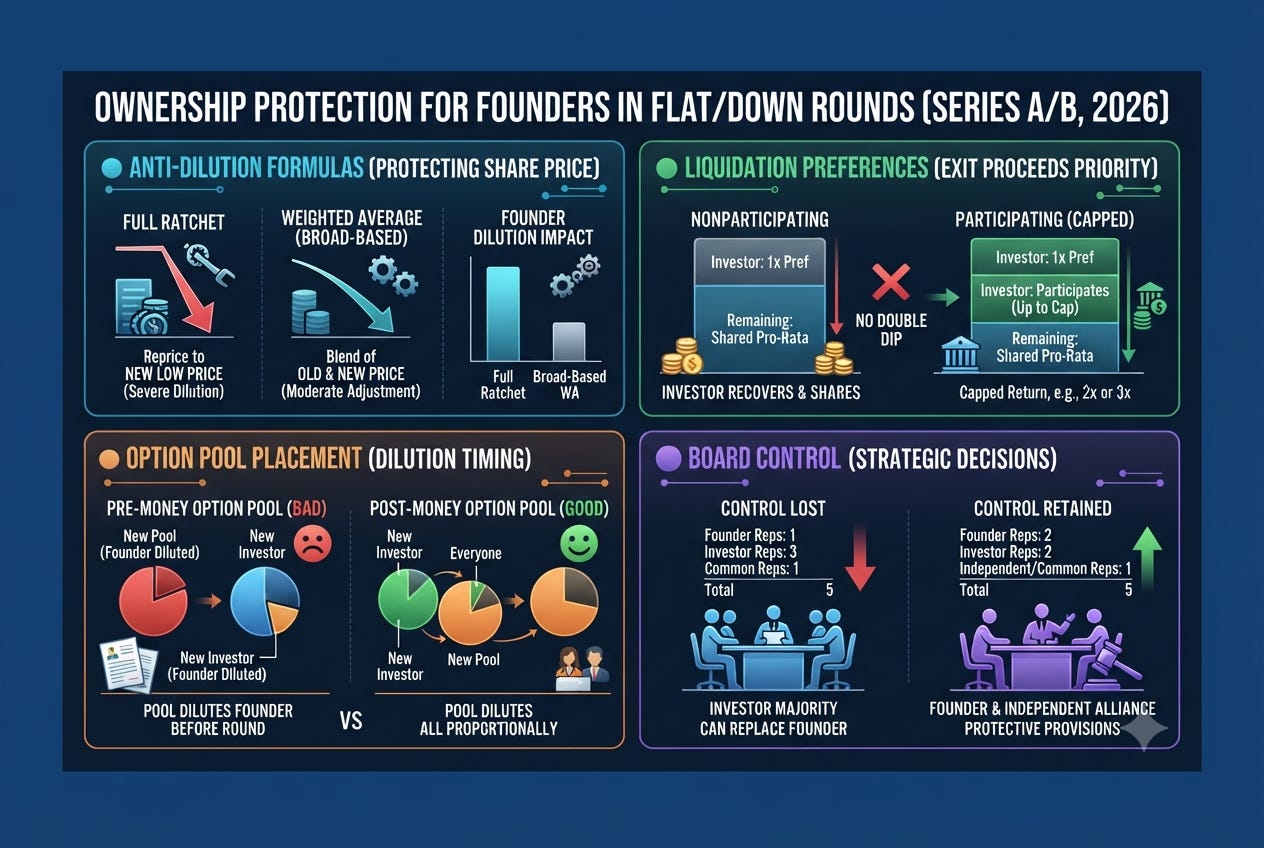
A founder who prices a Series A or Series B round flat or below the prior valuation in 2026 keeps control of the company through the anti-dilution formula, the participation cap, and the option pool placement, not through resisting the number on the cover page of the term sheet.
The clause that costs a founder the most equity in a down round is rarely the one the founder spends the negotiation fighting over. Founders fixate on the valuation, because the valuation is the number a board member, a spouse, or a competitor will ask about first. Investors know this, and a term sheet that concedes a lower price often arrives with a full ratchet anti-dilution clause, an uncapped participation right, or a pre-money option pool shuffle buried three pages later, each of which does more damage to founder ownership than the headline price cut itself.
The scale of the problem in 2026 is measurable. The combined down and flat pricing rate among Series B and later financings reached 28 percent in the fourth quarter of 2025. The aggregate down round rate across all financing stages has since eased to 11.4 percent by the first quarter of 2026, down from a peak above 20 percent in 2023, on a market that has bifurcated sharply: frontier artificial intelligence companies carried valuation premiums of 31 percent at Series A and 33 percent at Series B over non artificial intelligence peers in 2025, which means a company outside that category is negotiating against a comparable set pulled upward by financings that bear little resemblance to its own. Only 13 percent of companies that raised a Series A converted to a Series B within 24 months in the most recent cohort measured, and the median gap between the two rounds stretched to 28 months, the longest interval since 2012. A company running out of runway on that timetable arrives at the table with less room to negotiate price, which is precisely when the non-price terms decide the outcome.
Start with anti-dilution, because it sets the true cost of the down round. Full ratchet anti-dilution reprices every share of existing preferred stock to the new, lower price, regardless of how many shares the new round actually issued. Broad-based weighted average anti-dilution, the market standard in the overwhelming majority of United States venture financings, blends the old and new prices against the entire fully diluted capitalization, producing a far smaller adjustment on identical facts. A founder who sees full ratchet on a term sheet has grounds to reject it outright rather than negotiate around it, and should counter with warrant coverage instead: extra shares at a fixed strike price that compensate the new investor for risk without permanently subordinating the founder’s economic position in the capital stack.
Participating preferred stock deserves the same scrutiny. In a first quarter 2026 sample, 96.4 percent of financings still used nonparticipating preferred stock and 98.2 percent used a 1 times liquidation preference, meaning most investors take their money back first and then convert to common rather than double dipping into the remaining proceeds. Where a down round forces participating preferred onto the cap table, the fix is a cap, commonly two or three times the purchase price, after which the shares convert to common for any further distribution. Instabase, a document processing software company that had reached a 2 billion dollar valuation, raised 100 million dollars in January 2025 in a round led by the Qatar Investment Authority at 1.24 billion dollars, a cut of roughly 38 percent. The company kept operating on the new capital, which is the entire point of a properly structured down round: the price falls, the business continues, and the terms attached to that price determine how the smaller pie gets divided among founders, employees, and investors old and new.
In redlining these term sheets across market cycles, the clause founders miss most is not the anti-dilution formula they were warned to fear. It is the option pool shuffle: a new investor requires an expanded employee pool created before the money arrives, then calculates its own ownership percentage against a capitalization table that already includes that pool, so the founder alone absorbs the dilution from a pool the new investor will benefit from for years. Moving that pool to a post-money basis, or holding it to the size an actual eighteen-month hiring plan justifies, routinely returns one to two percentage points of ownership to the founder, worth real money at any exit above the smallest outcomes.
Pay-to-play provisions round out the list, and they cut both ways. These provisions, which force existing preferred stockholders to fund a pro rata share of the new round or suffer conversion to common stock, appeared in 42 percent of Series B and later deals in 2025, up from 27 percent in 2024. Used correctly, a pay-to-play clause clears passive investors out of the capitalization table and the boardroom to make room for a lead who is actually willing to fund the company through a hard market. Drafted broadly enough to sweep in founder-held common stock, the same clause becomes a lever the founder should have negotiated out before signing.
None of these terms move by themselves once the round closes. A founder who spends the negotiation on price and leaves the anti-dilution formula, the participation cap, the option pool placement, and the board seat to counsel’s boilerplate has already decided who controls the company at the next financing, whether that founder realizes it or not.
Interested in analysis about the intersection of venture capital, tech, artificial intelligence, public policy and the law? Check out my Substack channel. https://theinnovationattorney.substack.com/