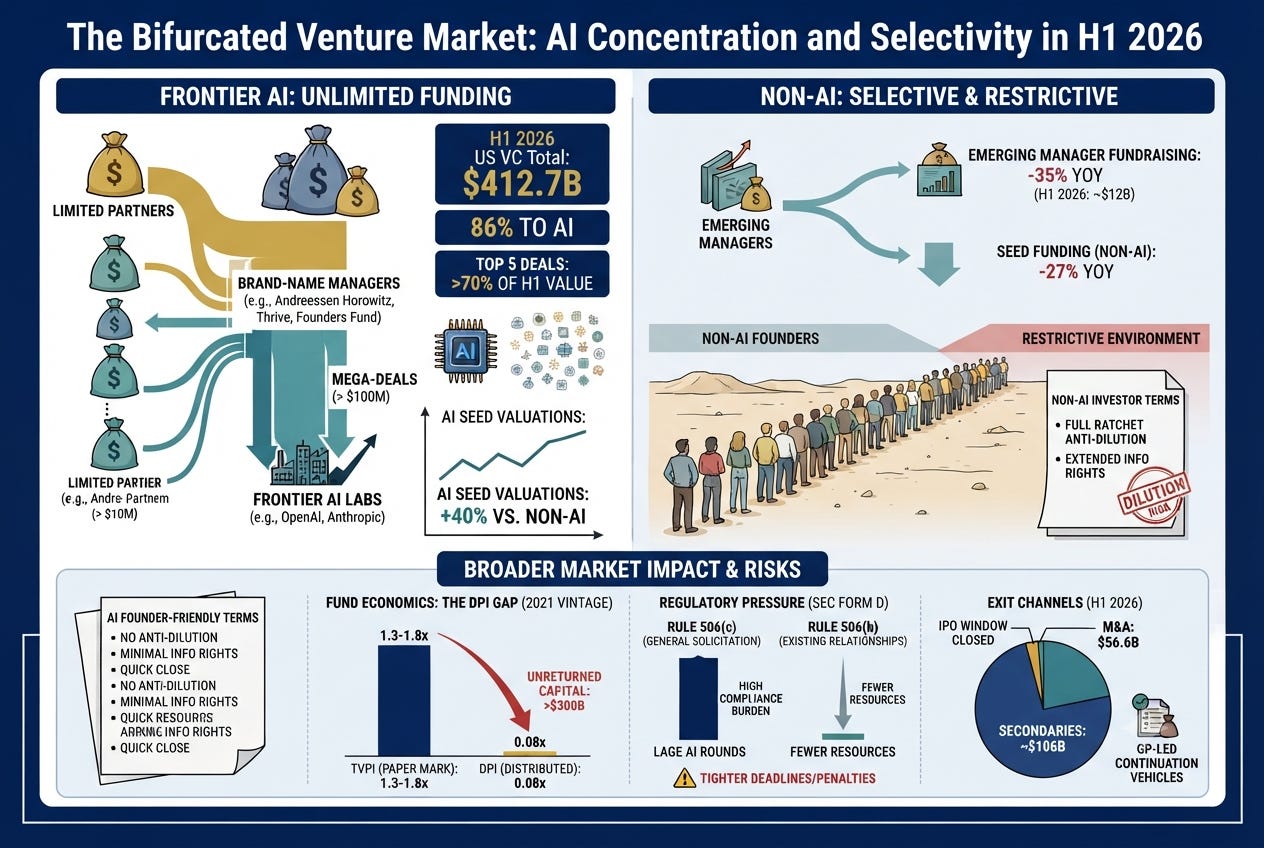
US venture capital funding hit $412.7 billion in the first half of 2026, surpassing all of 2025, and 86 percent of that capital went to artificial intelligence companies alone. Three venture firms captured just under half of all new fund commitments in the same period. Seed funding for companies outside artificial intelligence fell 27 percent year over year. The venture market did not simply grow in 2026. It split into two markets that share a name and almost nothing else.
This Substack is reader-supported. To receive new posts and support my work, consider becoming a free or paid subscriber.
The joint venture capital industry report covering the second quarter of 2026 is the closest thing this asset class has to an audited scoreboard, and this edition shows a market unrecognizable from three years earlier. Total dollars deployed are at a record. The number of distinct companies receiving meaningful capital, and the number of funds able to raise a next vintage, are both near multi year lows. Both facts are true in the same six months, in the same asset class, among many of the same investors.
Why AI Rounds Close Faster Than Everyone Else’s
Megadeals of $100 million or more captured 87.5 percent of total dollars deployed in the first half of the year, a threshold once reserved for late stage growth rounds and now common at seed and Series A for frontier AI labs. Two companies, OpenAI and Anthropic, accounted for 43 percent of global startup funding on their own, according to industry tracking published in the second quarter of 2026. The five largest US financings of the first half accounted for close to $200 billion, pushing the combined share of total venture deal value captured by the top five transactions past 70 percent. The mechanism behind this concentration reflects the underlying cost structure of frontier model development: training a frontier model requires computing capacity, specialized talent, and energy contracts priced in the billions of dollars, and the venture firms able to write financings of that size are the same firms whose brand names now draw the overwhelming share of new limited partner capital.
The redlines crossing my desk this past quarter illustrate the divide better than the aggregate figures do. AI seed and Series A term sheets for companies with a credible model or compute story routinely omit the full ratchet anti-dilution provisions and extended information rights that non-AI founders are now asked to accept as standard. Two founders raising identical dollar amounts at the same stage can end up ceding different percentages of their company depending on whether their product centers on a foundation model or an application built on top of one.
What Happened to Seed Funding Outside AI
Emerging manager fundraising, the source of most $500,000 to $5 million checks written into non-AI companies at seed stage, fell 35 percent year over year to approximately $12 billion in the first half of 2026, the lowest level since 2020. Seed valuations for AI companies now run roughly 40 percent above non-AI peers at the same stage, according to cap table data published in mid-2026. Non-AI founders are financing on a longer, more uncertain clock: rounds take longer to close, diligence runs deeper, and the investor base willing to lead a first check has narrowed.
With the initial public offering window largely closed through mid-2026 and merger and acquisition activity absorbing only $56.6 billion in the first quarter, secondary market transactions of approximately $106 billion have become a primary liquidity channel for venture-backed companies and their investors. General partner-led continuation vehicles, in which a fund manager transfers one or more portfolio companies into a newly formed vehicle backed by new secondary buyers, now give limited partners in older funds an exit option without waiting on a public listing or acquisition that may not arrive on the fund’s original timeline.
What the SEC’s Regulation D Agenda Means for Smaller Raises
Nearly every financing described here, from a $50,000 pre-seed note to a multi-billion dollar AI mega-round, relies on the same securities law exemption: Regulation D, Rule 506 of the Securities Act of 1933, filed with the Securities and Exchange Commission on Form D. Rule 506(b) permits an unlimited dollar amount raised from accredited investors without general solicitation, the structure most non-AI seed and Series A rounds still use because they close through existing relationships. Rule 506(c) permits general solicitation but requires the issuer to verify accredited investor status directly, a structure increasingly used by AI companies raising oversized rounds from a broad investor base. Issuers must file Form D within 15 days of the first sale of securities, and the Securities and Exchange Commission’s 2026 rulemaking agenda includes a plan to revisit a 2013 proposal that would tighten Form D filing deadlines and penalties, including a potential one-year bar from using the Regulation D exemption for issuers who file late or incompletely. A fund closing a $2 billion AI round and a founder closing a $2 million seed round rely on the identical exemption, so stricter Form D deadlines and penalties would land asymmetrically on the issuer with fewer resources to absorb a filing error.
Distributions to paid in capital for 2021 vintage funds sit at just 0.08 times committed capital, against reported multiples on invested capital in the range of 1.3 to 1.8 times, leaving more than $300 billion in capital unreturned to limited partners in holding periods that now regularly exceed seven years. Sixty percent of limited partners surveyed in mid-2026 said they now weight cash returned above the multiple a fund reports on paper. That shift in what limited partners will reward is the quiet force behind the concentration described throughout this piece: capital is not simply chasing artificial intelligence, it is chasing the managers who can show cash back in an unforgiving fundraising market.
Whether reported revenue at the largest AI labs reflects recognized, collected revenue or forward committed contracts remains disputed among data providers, and whether emerging managers can rebuild limited partner relationships before capital dries up further outside artificial intelligence are the two questions that will define the second half of 2026 more than any single financing round.
See my full analysis here: https://theinnovationattorney.com/the-bifurcated-venture-market-ai-concentration-and-selectivity-in-h1-2026/